Gold Stuck Below the 4400 Level: Who Is Repricing the Discount Rate After the Fed Rate Hike?
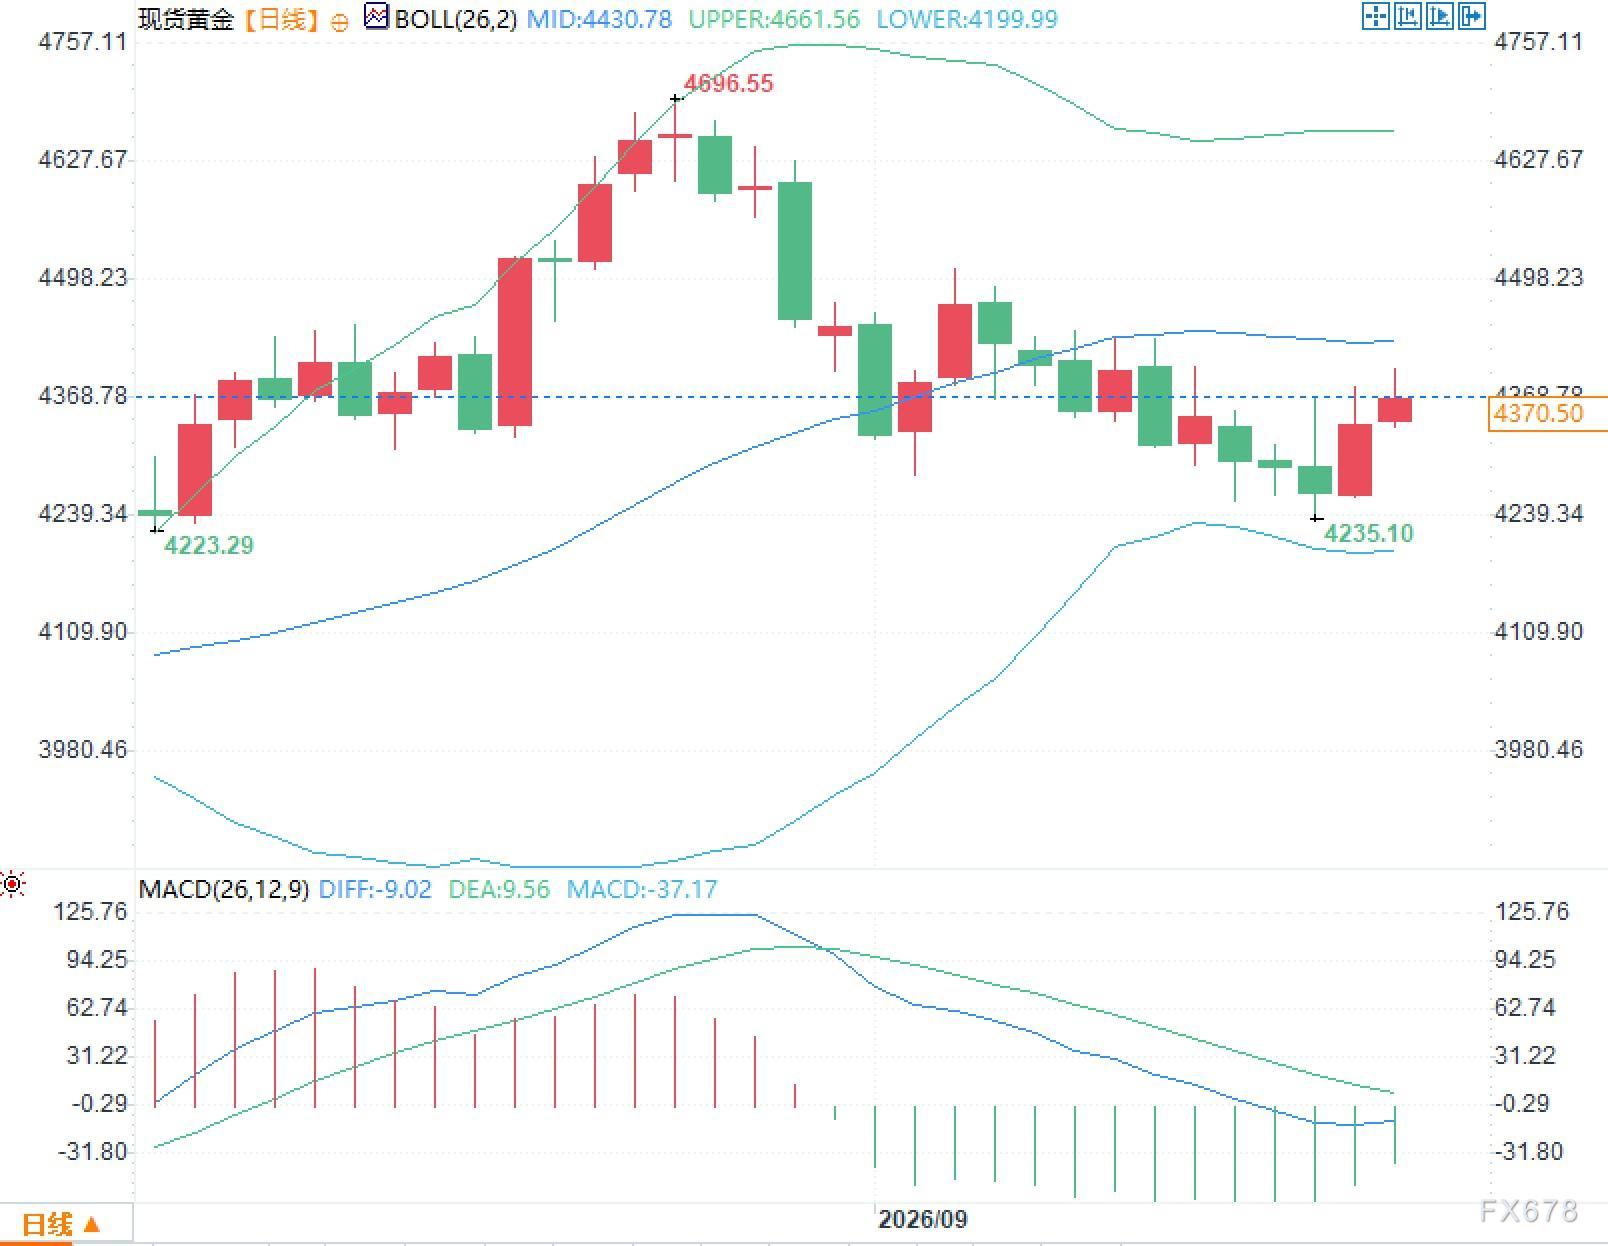
Huitong Finance, September 18— On Friday, September 18, spot gold was trading amid intense repricing following the Federal Reserve's first rate hike in three years, currently fluctuating around $4,370, up about 0.6% intraday and still slightly away from the $4,400 round number threshold. The US 10-year Treasury yield remains near 4.96%, with a weekly high of 5.04%. US crude oil has retreated from its highs and is now trading around $97. The simultaneous shifts in rate trajectory, energy premium, and non-yielding asset holding costs all in the same week form the central contradiction in current gold pricing.
On Friday, September 18, spot gold was trading amid intense repricing following the Federal Reserve's first rate hike in three years, currently fluctuating around $4,370, up about 0.6% intraday and still slightly away from the $4,400 round number threshold. The US 10-year Treasury yield remains near 4.96%, with a weekly high of 5.04%. US crude oil has retreated from its highs and is now trading around $97. The simultaneous shifts in rate trajectory, energy premium, and non-yielding asset holding costs all in the same week form the central contradiction in current gold pricing.
The Median Policy Outlook After the Fed Rate Hike Is Tougher Than the Decision Itself
Recently, the Federal Open Market Committee voted unanimously, 12-0, to raise the federal funds rate target range by 25 basis points to 3.75%–4.00%. This is the first rate hike since 2023. The decision itself was largely in line with market pricing, but what truly shifted the curve was the Summary of Economic Projections. The dot plot shows that 16 of the 18 policymakers submitting forecasts expect at least one more rate hike this year, with the median policy rate at 4.1% at the end of both 2026 and 2027. This means the official path no longer writes 2027 as a rate-cutting year, but prolongs the period rates remain in a higher range.
Federal Reserve Chair Walsh explained the logic very plainly at the post-meeting press conference. He stated that inflation is too high and has lasted too long; this summer's data does not show fundamental progress in the underlying trend. Based on the latest consumer and producer price indices, August’s headline personal consumption expenditures (PCE) price index is estimated at 3.6% year-on-year, with the committee forecasting 3.7% for the full year and a decrease to 2.3% next year. The unemployment rate is projected around 4.1%, with real GDP growth forecast at 2.3% this year and 2.4% next year. Walsh also said it is hard to describe current broad financial conditions as restrictive, so this action is merely removing some accommodation. The market interpreted this as: the committee does not believe it has yet set policy tight enough.
Rate futures are pricing the probability of another Fed hike at the October meeting at around 50%, with the odds of an additional hike by December much higher than for October alone. For gold, the key is not whether the next meeting delivers a hike, but how long the risk-free rate remains above 4%. Gold pays no interest, and the cost to hold it rises in tandem with real and nominal yields. The US dollar index’s rise to a seven-week high is simply a reflection of the same pricing logic in foreign exchange, not a separate story.
Crude's Pullback Opens Gold’s Rebound Window, but the Energy Premium Persists
This week, gold rebounded from around $4,235, with the direct trigger not a sudden dovish turn in rate expectations, but a retreat in oil prices from their highs, which pulled US Treasury yields off their peaks. Last week, Saudi Arabia’s east–west oil pipeline was attacked and temporarily shut down. This pipeline could ship crude to the Red Sea, reducing reliance on the Strait of Hormuz. The market then learned that repairs were underway, some exports were rerouted, and additional supply was sent to Asian refineries via ship-to-ship transfers near Sohar, Oman. As oil retraced, the 10-year US Treasury yield fell from about 5.04% down to near 4.96%.
The pullback is still limited. Passage through the Strait of Hormuz has not returned to normal; transiting vessels remain well below recent averages, and energy-related inflation risks have not been removed from the pricing equation. As long as oil stays in a high range, inflation expectations are unlikely to be systematically revised down, so long-end US yields lack the conditions for sustained declines. This gold rally looks more like a correction of excessive hawkish reaction post-hike, combined with a yield breather due to oil’s retreat, rather than a removal of the cost constraint on holding gold.
The geopolitical agenda will continue to feed into the energy premium next week. During the United Nations General Assembly, the US president is expected to meet with Gulf Cooperation Council leaders or foreign ministers on September 22 to discuss follow-up arrangements regarding Middle East conflicts. The president recently stated that Iran is willing to engage. These statements do not change inventories or shipping capacity by themselves, but will alter the slope of oil’s risk premium, which then transmits to gold via inflation expectations and real rates. If diplomatic cooling is accompanied by a deeper oil pullback, yields would have room to fall from highs; if transportation through the strait or pipeline repairs falter, the energy premium would again press long-term yields higher.
Holding Cost Runs Parallel With Official Demand
Two fundamental forces exist in parallel. On one hand, holding cost: the Fed’s median policy rate is anchored at 4.1%, the 10-year Treasury yield approaches 5%, and the opportunity cost of non-yielding assets remains elevated. On the other, physical and allocation demand: Official global demand net gold buying in Q2 was about 289 tons, with the first half totaling around 345 tons, as central banks including Poland kept accumulating. In August, gold ETFs saw a wave of concentrated inflows, with North America accounting for about $7.7 billion in a single month and global inflows at about $18 billion; total global ETF assets managed rose to around $615 billion, with holdings of about 4,189 tons. The pace of central bank buying and fund flows fluctuates with price and rates, but both provide a medium-term reserve and allocation base, giving gold liquidity for rebounds after rate shocks.
The Bank of Japan today raised its policy rate by 25 basis points to 1.25%, citing inflation risks from rising oil prices. The simultaneous tightening by major economies lifts the global neutral real rate, making gold’s relative attractiveness more dependent on real rates coming down, rather than nominal gold price movements alone.
Next Week’s Watch Window: Fed Speeches and Data Revisions
The US economic calendar is relatively light next week, with more focus on public speeches from Fed officials. The market needs to identify two things in their remarks: whether an October hike is described as the base path or as a data-dependent option; and whether the pullback in energy prices is acknowledged as inflation relief or still deemed unstable. Walsh’s standard is already clear: there must be confidence that underlying inflation is moving toward 2% at a sufficient pace. If officials repeat this benchmark, October’s rate hike odds in the futures market are likely to continue hovering near 50%; only if oil’s retreat is cited as improving inflation conditions will yields have further room to drop.
Data will also be crucial. After positioning and policy expectations hit their limits, even mild data surprises will reshuffle probabilities on the rate path. If subsequent inflation and demand data come in weaker than the 3.7% inflation path in committee forecasts, markets will lower the odds of a second hike this year; if data tracks close to or exceeds forecasts, the 4.1% median will shift from the dot plot into the futures curve. Gold’s reaction to this process usually first appears in real rates and the dollar index, then in volatility of the metal itself.
From a medium-to-long-term perspective, official gold buying, investment demand, and gold ETF flows provide solid reserves and allocation support; in the short term, the median policy rate, Treasury yields, and the dollar index determine the discount rate. The presence of both forces explains why gold was able to rebound after the Fed’s rate hike this week but found it hard to firmly break above the key round-number threshold.





