
Amended class action calls Pump.fun a ‘slot machine cabinet’ in $5.5B case

An amended class-action complaint filed in the Southern District of New York alleged that memecoin platform Pump.fun operated as a “front-facing slot machine cabinet” in extracting more than $5.5 billion from users through deceptive digital asset schemes.
The lawsuit, filed on Wednesday, named Pump.fun’s operators, including pseudonymous developer Bernie, parent company Baton Corp., and infrastructure partners including Solana Labs, the Solana Foundation, Jito Labs and the Jito Foundation as defendants.
The case accused them of engaging in a coordinated enterprise functionally similar to an “unlicensed casino,” relying on volatility and hype rather than disclosures or investor safeguards.
“The structure mimics a rigged slot machine where the first few players win by dumping their tokens on later ones. There is no underlying project, product, or revenue — only a fast-moving cycle of buying, dumping, and collapse,” the filing alleges.
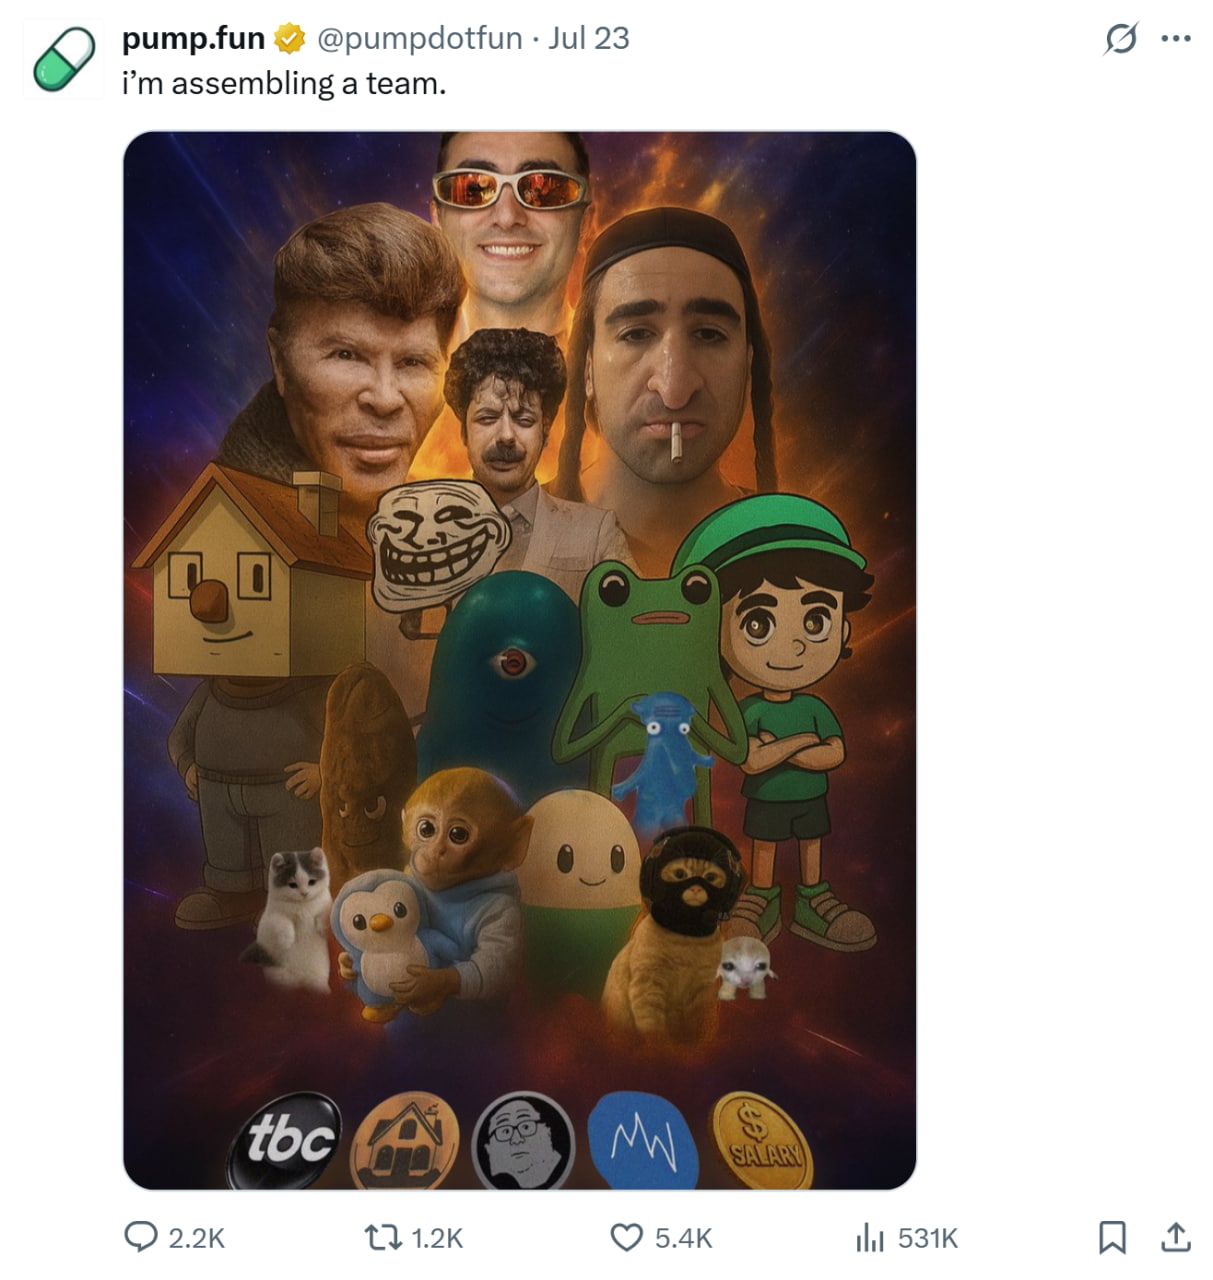 A recent post on X by Pump.fun. Source: Pump.fun
Amended Pump.fun lawsuit adds more claims
The amended complaint also escalates the scope of the alleged misconduct. It includes Racketeer Influenced and Corrupt Organizations Act (RICO) claims, fraud, aiding and abetting, civil conspiracy and unjust enrichment.
Plaintiffs seek rescission of all Pump.fun transactions and compensatory damages for purported harm caused by what they call a “rigged” system.
The lawsuit alleges Solana-affiliated entities played a role in facilitating the scheme. “Solana Labs and the Solana Foundation provided the venue — the Solana blockchain itself — and monetized each wager through the sale of block space, validator fees and SOL token appreciation,” the plaintiffs claim.
Furthermore, the filing points out the role of liquidity infrastructure provided by Jito Labs and Jito Foundation, which allegedly earned revenues through maximum extractable value strategies tied to memecoin trading on Pump.fun.
The lawsuit was originally filed in January this year. At the time, it claimed that Pump.fun used guerrilla marketing to generate artificial urgency for “highly volatile” tokens from which it made nearly $500 million in fees.
Cointelegraph reached out to Pump.fun’s co-founder, Alon Cohen, on X for comment but had not received a response by publication.
Pump.fun token tanks as early investors sell
On Tuesday, two major early investors in Pump.fun’s PUMP token offloaded over $160 million worth of tokens to exchanges, triggering fears of a broader sell-off.
Wallets dubbed “PUMP Top Fund 1” and “Top Fund 2” had acquired $150 million worth of tokens during a private round but have since deposited nearly their entire holdings to exchanges, with only $29.5 million remaining in one wallet.
Nearly 60% of PUMP early backers have sold or transferred their tokens , according to BitMEX. Analysts say the token’s large initial unlock likely contributed to downward price pressure, despite its strong start.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
JPMorgan brings JPM Coin to Ethereum
Nvidia invests billions of dollars in Germany; Jensen Huang: Once a technology powerhouse, the country has fallen behind, which pains me deeply
Nvidia signed a memorandum of cooperation with the German government at the "Invest in Germany" summit in Berlin, investing in four German startups covering robotics, healthcare, generative AI, and satellite sectors. The company also partnered with Siemens to develop AI factory solutions, potentially reducing costs by up to 20%. Jensen Huang expressed regret that Germany is lagging behind in the technology competition, noting that Europeans may be overly hesitant and consider too many factors when taking action.

The most direct signal that US stocks have peaked: South Korean chip exports?
Currently, the U.S. stock market is supported solely by strong earnings expectations. If semiconductor exports from South Korea and Taiwan decline, it may provide an early warning 3-6 months in advance of capital expenditure peaking. Once expectations reverse, high yields will instantly crush valuations.

CoreWeave Credit Crisis Resembles the 2023 SVB Panic More Than the 2008 Subprime Mortgage Crisis?
The key issue now is not whether CoreWeave will collapse, but whether compute pricing can support the financing logic of this cycle. The answer to this question will determine the eventual outcome of this panic.

Crypto prices
More


