
Netflix (NFLX) Q4 Earnings Preview: Warner Merger Uncertainty and Ad Business Momentum
1.Investment Highlights Overview
Netflix is slated to release its Q4 2025 financial results after the market close on January 20, 2026, with consensus estimates projecting revenue of $11.97 billion (+16.8% YoY) and EPS of $0.55. Key investor focus lies on the ad-supported tier's expansion potential and the ongoing Warner Bros. Discovery (WBD) acquisition drama, which could reshape competitive dynamics. Amid a year-to-date stock decline exceeding 30% in 2025, this report serves as a pivotal test of Netflix's shift toward sustainable profitability and cash generation, heightening scrutiny on earnings quality amid global risks.
2. Four Key Focus Areas
Focus 1: Ad Tier Expansion
The ad-supported plan emerges as a vital growth lever, directly bolstering overall margins through enhanced monetization. With monthly active viewers hitting 190 million in Q3 2025, holiday season demand could further elevate average revenue per user (ARPU) relative to standard plans. Strong performance here might solidify confidence in doubling ad revenues for 2026, potentially offsetting slower subscriber additions in saturated markets and supporting stock recovery.
Focus 2: Warner Acquisition Developments
The proposed $82.7 billion enterprise value deal for Warner Bros. introduces major uncertainty, including regulatory hurdles and financing tweaks amid a rival higher bid from Paramount Skydance. Successful integration could enrich content libraries and live sports offerings, strengthening Netflix's edge in a fragmented industry. Positive updates from management, such as a shift to an all-cash structure, could ease dilution fears and stabilize shares; prolonged delays, however, might intensify downward pressure toward the $85 support level.
Focus 3: Profit Margins and Cash Flow
Maintaining robust margins amid annual content investments exceeding $17 billion tests Netflix's maturity as a cash-generating powerhouse. Q3 2025's adjusted operating margin neared 33% (post-Brazil tax adjustment), but international exposures remain a wildcard. Solid Q4 free cash flow could fuel share buybacks and valuation uplift; persistent cost overruns from content or regulations might erode investor trust in long-term earnings stability.
Focus 4: Content Pipeline and Live Sports
Transitioning to live events like NFL Christmas games and boxing matches gauges platform stickiness and ad conversion efficiency. A strong lineup could mitigate easing subscriber growth by drawing premium audiences. Metrics like live viewership exceeding forecasts would reinforce diversified revenue streams; underwhelming engagement might heighten concerns over competition from traditional broadcasters.
3. Risks and Opportunities Coexist
Upside Catalysts:
Ad revenues surpassing expectations, fueled by seasonal boosts and higher penetration rates, could directly enhance overall growth and margins. Favorable Warner merger progress, including regulatory nods or optimized terms, might unlock synergies in content and sports. Exceptional live sports performance could attract high-engagement users, accelerating both subscriptions and ad income.
Downside Risks:
Unexpected international tax or regulatory setbacks, akin to the Brazil case, could erode profits and amplify operational uncertainties. Stalled or escalated merger costs from competing bids might trigger equity dilution and institutional selling. Persistent U.S. subscriber softness, if not offset by ads, could signal market saturation and weigh on valuations.
4. Trading Strategy Insights
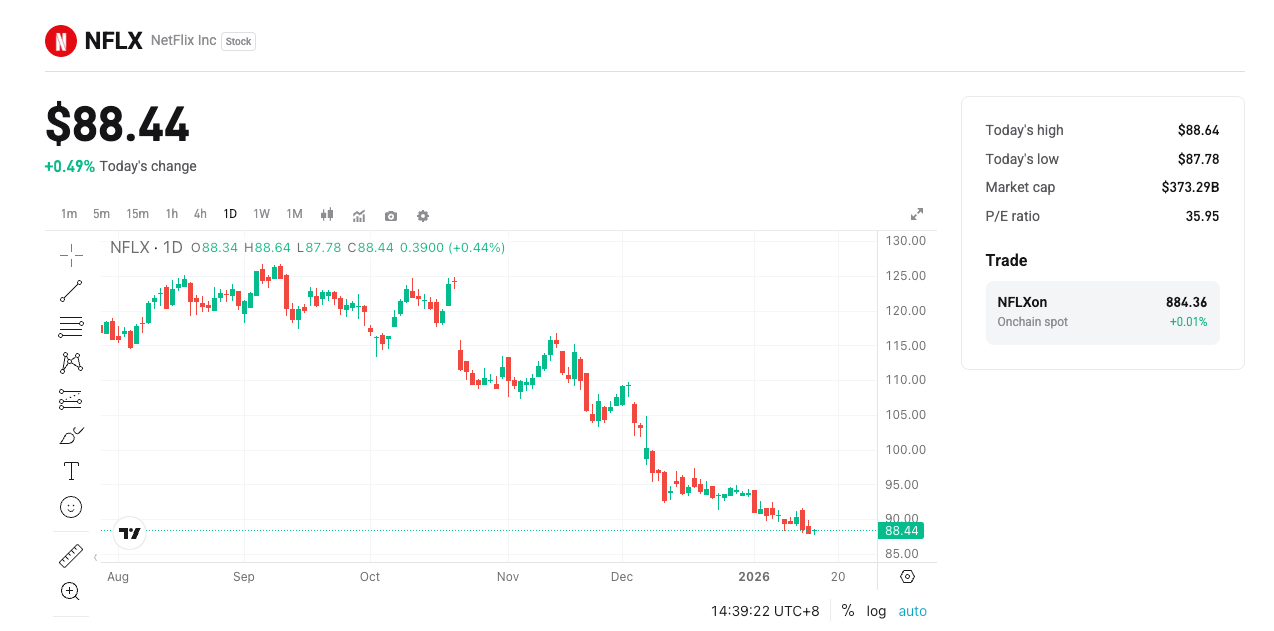
- Bullish Case: If revenue and EPS beat estimates alongside reassuring Warner updates minimizing dilution risks, shares could rally past the $94 resistance, offering upside potential.
- Bearish Risks: Subpar ad growth or adverse merger news might breach $88 support, with possible dips to $82-$85.
- Key Metrics: Revenue $11.97 billion, EPS $0.55, operating margin (target near 33%), and ad tier monthly active viewers.
Disclaimer: The above content is compiled through AI searches and verified manually for release only; it does not constitute any investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
From the Token Frenzy to the $1.3 Trillion AI Server Blue Ocean: AI Inference Computing Power Fully Explodes, Industry Leaders like Dell Usher in the Golden Era of "Volume, Price, and Market Share"
Leading global AI server cluster manufacturers such as Dell are simultaneously benefiting from two major growth dividends: the accelerated expansion of the AI server market and a significant increase in the order shares from core AI cloud computing customers, including large enterprises and new cloud providers. They are not merely passively profiting from hardware price increases.

GPU Cloud Services Surge in Price: Nebius Raises Prices Again by 20%, Computing Power Supply Side Gains Bargaining Power
From October 1st, Nebius will raise prices for its entire GPU cloud service line by approximately 20%, with multiple chips from H100 to B300 seeing increases. This marks the second round of price hikes in recent months, and the cumulative increase for B300 has reached 56%. Demand visibility extends beyond 24 months, with customers eager to purchase Blackwell computing power, even willing to pay a premium in auctions. The supply-demand imbalance for AI computing power is reshaping the entire industry’s negotiation landscape, as bargaining power is quietly shifting to the supply side.


Crypto prices
More


