
Chipotle's Pricing Lags Inflation: How Deep Is the Margin Squeeze?

Chipotle Mexican Grill, Inc. CMG enters 2026 with a visible pricing-to-inflation dislocation, shaping its near-term margin outlook. Management expects full-year pricing to rise about 1% to 2%, while overall inflation is projected in the 3% to 4% range. This gap implies roughly 150 basis points (bps) of year-over-year restaurant-level margin pressure in 2026.
The imbalance is most pronounced in the first quarter. With pricing contributing about 70 bps to comparable sales and inflation running near 4%, the resulting spread is expected to translate into roughly 250 basis points of restaurant-level margin pressure. Although management noted that the pricing-to-inflation gap will narrow as the year progresses, margins are expected to remain under pressure.
Additional cost factors also weigh on margins. Inflationary costs are concentrated in beef, avocados and cooking oils, with full-year cost of sales inflation anticipated in the mid-single-digit range. Although tariff impacts are moderating (from approximately 30 bps in the fourth quarter of 2025 to an anticipated ongoing effect of roughly 15 bps in 2026), other cost pressures, including marketing spend (projected in the low-3% range of sales), add to the margin strain.
Over the longer term, management views the margin compression as cyclical rather than structural. Productivity initiatives, operational efficiencies, equipment enhancements and scale benefits are expected to support gradual rebuilding toward the high-20% margin range. For 2026, the pricing-to-inflation dislocation remains the central factor shaping restaurant-level margin performance.
CMG’s Stock Price Performance, Valuation & Estimates
Shares of Chipotle have plunged 37.2% in the past year compared with the industry’s fall of 6.6%. In the same time frame, other industry players like Starbucks Corporation SBUX, Sweetgreen, Inc. SG and CAVA Group, Inc. CAVA have declined 14%, 81.1% and 51.4%, respectively.
CMG One-Year Price Performance
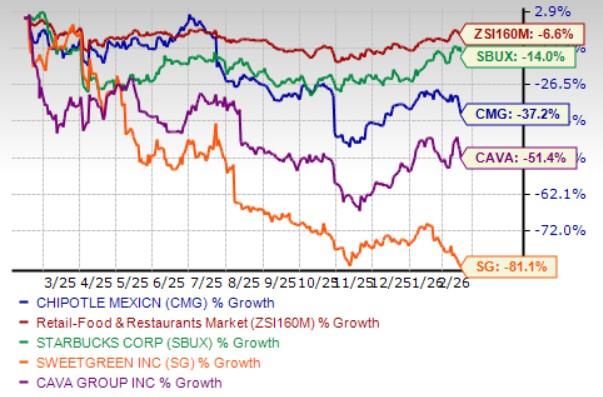
Image Source: Zacks Investment Research
From a valuation standpoint, CMG trades at a forward price-to-sales (P/S) multiple of 3.56, below the industry’s average of 3.75. Conversely, industry players, such as Starbucks, Sweetgreen and CAVA, have P/S multiples of 2.81, 0.8 and 5.14, respectively.
CMG’s P/S Ratio (Forward 12-Month) vs. Industry
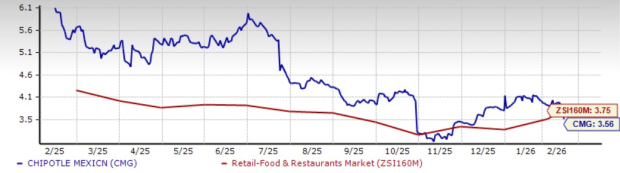
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for CMG’s 2026 earnings per share has declined in the past 30 days.
EPS Trend of CMG Stock
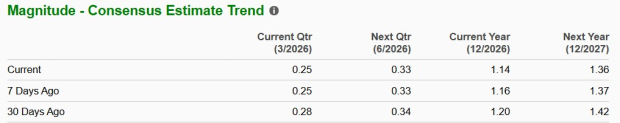
Image Source: Zacks Investment Research
The company is likely to report soft earnings, with projections indicating a decline of 2.6% in 2026. Conversely, industry players like Sweetgreen and CAVA are likely to witness an increase of 12.7% and 6.7%, respectively, year over year, in 2026 earnings. Meanwhile, Starbucks' fiscal 2026 earnings are likely to witness a rise of 8.5% year over year.
CMG stock currently has a Zacks Rank #5 (Strong Sell).
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
AUD/JPY Price Forecast: Holds gains above 110.50, but maintains bearish bias below 100-day SMA
Hollywood Plans "Film Production Reshoring"! US Economic "Soft Landing" Welcomes a $249.1 Billion Film Incentive Blueprint
A study shows that federal incentives for film and television production will bring $249.1 billion in revenue to the U.S. economy by 2035 and add 143,500 full-time jobs. The Motion Picture Association has been working with Hollywood unions to launch a campaign for national incentives to better compete with markets such as the United Kingdom and Australia.

Tonight, a "dovish rate hike"?
The Federal Reserve is almost certain to raise interest rates tonight, but the key issue is "what will be said after the hike." Citi characterizes this move as a "fine-tuning" adjustment, suggesting there is no inevitable future rate hike, yet warns that if Chairman Powell does not provide clear forward guidance, it will trigger significant market volatility. Goldman Sachs bluntly stated that there is insufficient economic foundation for this rate hike, with inflation being merely a one-off factor, and expects this to be a "signal-less rate hike."
JPMorgan: "Open source disruption" and "AI safety" are not issues, there is still room for capital expenditure in the next two years, semiconductor equipment will become the "new bottleneck"
JPMorgan believes that open-source models are not a threat, regulatory disruptions are only short-term, and cloud vendors’ leverage remains low—the fundamentals of computing power investment have not changed. It forecasts that the capital expenditure of the seven major tech giants will soar from $443 billion in 2025 to $1.577 trillion in 2027, with semiconductor equipment becoming the core bottleneck of the supply chain and a new round of price increases expected in wafer foundry and advanced packaging.
Crypto prices
More


