
Here's Why Boot Barn's Store Expansion Strategy Looks Compelling

Boot Barn Holdings, Inc. BOOT continues to generate strong results from its new store engine, consistently surpassing expectations for sales, earnings, and payback across all U.S. regions. This momentum has carried through stores opened over the past 12 months. The company ended the fiscal third quarter with 514 locations, including a record 25 openings during the quarter, while reaffirming its long-term goal of reaching 1,200 stores nationwide.
The expansion strategy is supported by attractive unit economics. New stores are projected to deliver roughly $3.2 million in annual sales in their first full year. Management expects these locations to recover their initial investment in under two years, highlighting strong early productivity and compelling returns on new units.
Growth in non-legacy markets such as Florida, Jersey City, and the Northeast has been especially encouraging. Management noted that the sales mix and customer profile in these regions closely resemble legacy markets like California, Arizona and Texas, demonstrating the brand’s nationwide resonance and competitive positioning.
Overall, Boot Barn’s store expansion pipeline remains strong. The company plans to open 15 stores in the fiscal fourth quarter, bringing fiscal 2026 openings to 70 stores. Looking ahead, for fiscal 2027, about 20 openings are planned for the first quarter beginning in April, with annual new unit growth targeted in the range of 12% to 15%, reinforcing sustained expansion and earnings growth potential.
The Zacks Rundown for BOOT
BOOT’s shares have gained 5.4% year to date compared with the industry’s rise of 3.9%. BOOT sports a Zacks Rank #1 (Strong Buy).
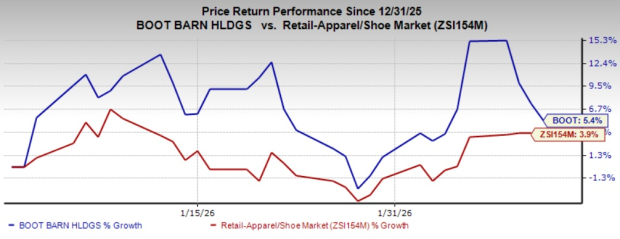
Image Source: Zacks Investment Research
From a valuation standpoint, BOOT trades at a forward price-to-earnings ratio of 22.17, higher than the industry’s average of 18.38.
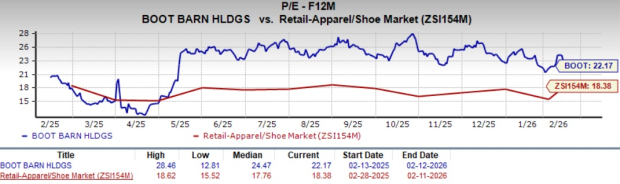
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for BOOT’s current and next fiscal year earnings implies a year-over-year rise of 26% and 16.1%, respectively.
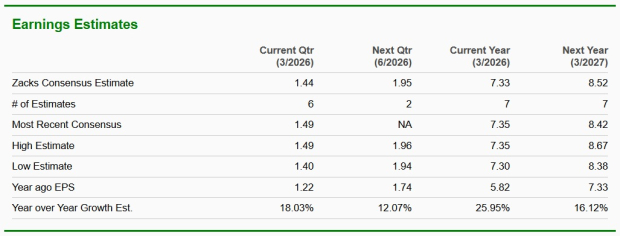
Image Source: Zacks Investment Research
Other Stocks to Consider
Five Below, Inc. FIVE operates as a specialty value retailer in the United States. At present, Five Below currently sports a Zacks Rank of 1.
The Zacks Consensus Estimate for FIVE’s current fiscal-year sales and earnings implies growth of 22.4% and 25.8%, respectively, from the year-ago figures. FIVE delivered a trailing four-quarter earnings surprise of 62.1%, on average.
American Eagle Outfitters, Inc. AEO operates as a specialty beauty retailer in the United States, Mexico and Kuwait. At present, AEO flaunts a Zacks Rank of 1.
The Zacks Consensus Estimate for AEO’s current fiscal-year sales implies growth of 2.6%, and the same for earnings indicates a decline of 20.7% from the year-ago figures. American Eagle delivered a trailing four-quarter earnings surprise of 35.1%, on average.
Deckers Outdoors Corporation DECK, together with its subsidiaries, designs, markets and distributes footwear, apparel, and accessories for casual lifestyle use and high-performance activities in the United States and internationally. At present, Deckers sports a Zacks Rank of 1.
The Zacks Consensus Estimate for DECK’s current fiscal-year sales and earnings indicates growth of 8.5% and 7.9%, respectively, from the year-ago figures. DECK delivered a trailing four-quarter earnings surprise of 36.9%, on average.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Wall Street giants’ trading operations show a tale of two extremes: JPMorgan (JPM.US) expects a surge in Q3 performance, while Bank of America (BAC.US) warns of a slowdown
JPMorgan predicts that trading and investment banking income will see double-digit growth in Q3, triggering a rebound in its stock price. Previously, Bank of America warned of flat revenue due to a pullback in financing, leading to a sell-off in the sector.

Trillion-dollar defense budget in sight, Guggenheim strongly recommends defense stocks, L3Harris Technologies (LHX.US) is the top large-cap pick
Guggenheim Securities recently initiated coverage of 22 aerospace and defense companies, with an overall positive outlook on defense contractors and aircraft manufacturers, but a cautious attitude toward commercial aviation aftermarket suppliers.

Tokenized funds expand across chains, yet liquidity remains fragmented – Why?
Japan Reportedly Plans to Double Defense Spending to 3.5% of GDP, Ministry of Defense Denies, Yet Japanese Bond Yields Hit 30-Year High
According to reports, Japanese defense officials have expressed their willingness to significantly increase defense spending during meetings with the United States. One proposal is to raise defense spending to 3.5% of GDP within ten years, while another, lower target is 3%. Japanese officials previously stated that this fiscal year's defense and related expenditures are approximately $68.8 billion, equivalent to about 1.9% of Japan's nominal GDP in 2022.
Crypto prices
More


