
J.P. Morgan: Global crude oil inventories enter pressure range in late June, bottom out in September

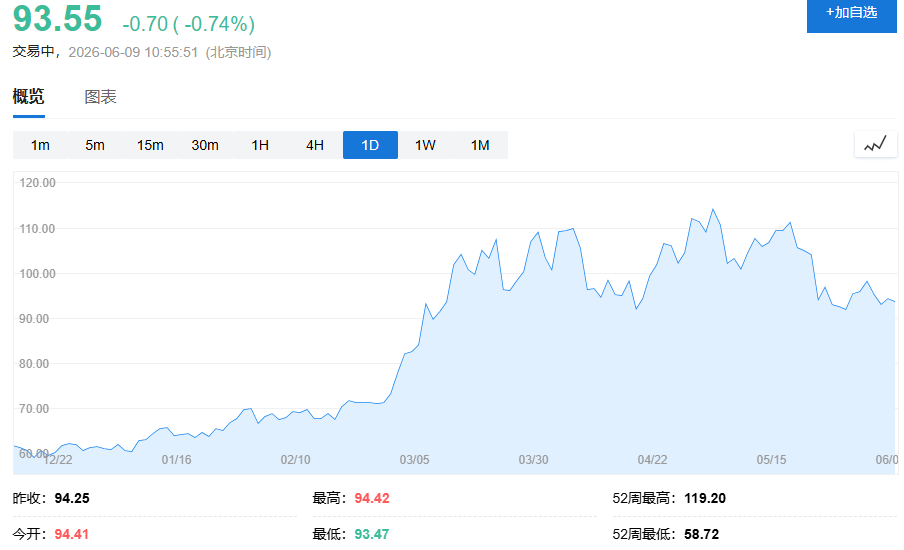
On June 9 local time, Natasha Kaneva, Head of Commodities Research at JPMorgan, indicated in the latest weekly report that four months into the Iran-Israel conflict, market prices remain relatively calm — Brent crude oil futures are stable around $100/barrel, with volatility having dropped significantly.
Does this calm mean the worst is over? Or is the market underestimating a delayed shock?
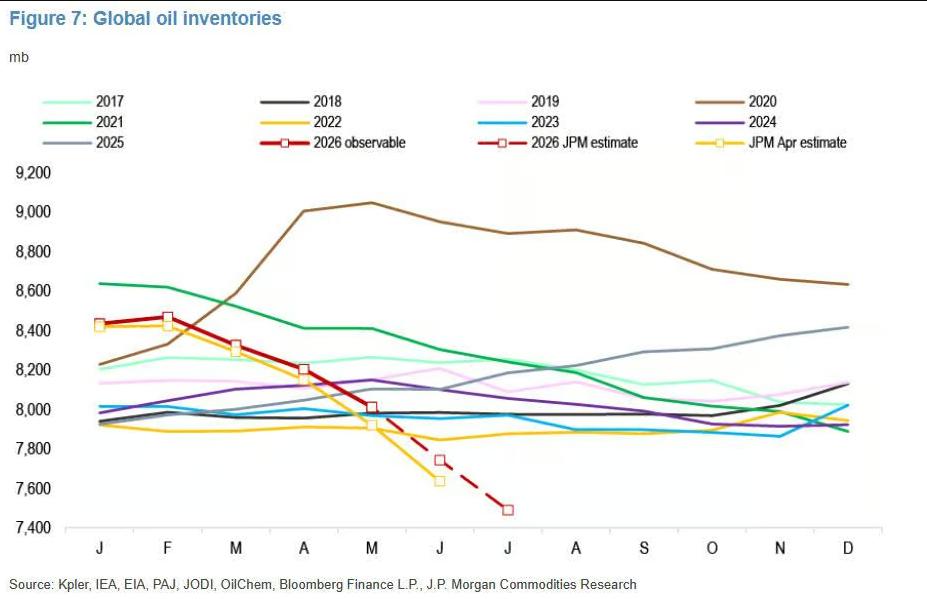
Kaneva’s answer is: the cushion mechanisms of declining oil demand and global capacity expansion are temporarily supporting prices, but the clock is still ticking on inventory depletion. Since early March, total visible global crude inventories have dropped by about 460 million barrels. Analysts expect inventories to enter a pressure zone in late June and approach operational thresholds by September.
About 2.1 million barrels still quietly pass through Hormuz Strait daily
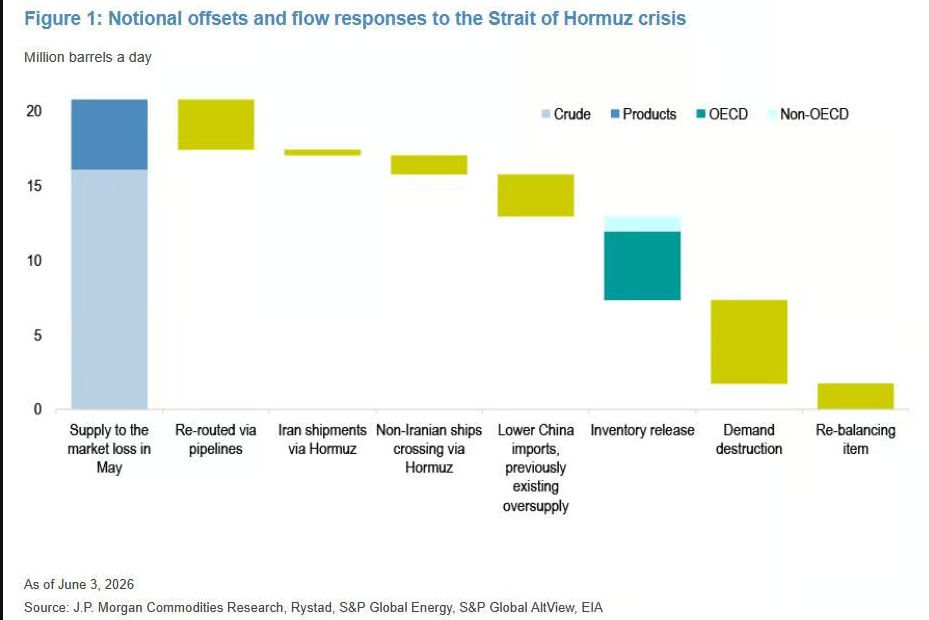
The Strait of Hormuz is nominally blocked, with visible vessel traffic at roughly 15% of pre-war levels. But the actual situation is more complex.
Some vessels have turned off their transponders or falsified signals, silently crossing the strait. Analysts estimate that in the second half of May, “invisible flows” through the strait amounted to about 2.1 million barrels per day, and some institutions’ estimates are even wider, ranging from 1.5 to 3 million barrels per day.
Notably, the number of visible crossings in the past two weeks nearly doubled compared to early May, with more and more vessels “hopping” across the strait while their transponders are off.
However, this is still far from enough to fill the gap — pre-war, Hormuz handled about 16 million barrels per day.
Non-Gulf producers attempt to fill the gap, but it’s just a drop in the bucket
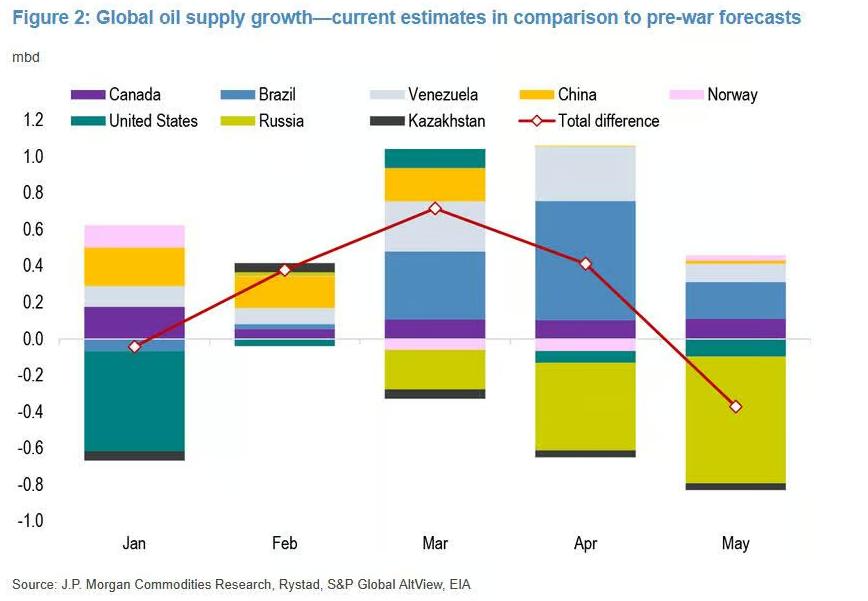
On the supply side, oil-producing countries in the Americas are running at full throttle.
From January to April, Brazil's production rose by 800,000 barrels per day year-on-year — about 200,000 barrels higher than analysts’ expectations; Venezuela’s production was up by 360,000 barrels per day, also about 200,000 barrels above projections. In the US, liquid fuels output rose by 800,000 barrels per day from March to May year-on-year, and since April there has been a massive strategic petroleum reserve release, pushing exports to record highs — April exports rose by 2.5 million barrels per day and climbed a further 3 million barrels per day in May.
But Russia became a drag. Ongoing Ukrainian drone attacks on Russian refineries and export terminals have meant Russia’s April output was 500,000 barrels per day below expectations, and 700,000 barrels per day lower in May.
Overall, net new supply from non-Gulf regions was about 2.1 million barrels per day in March, 2.4 million barrels per day in April — a huge shortfall compared to the 16 million barrels lost daily from the Middle East.
Global seaborne crude imports fell drastically from 45.4 million barrels per day in February to 36.4 million in April, rebounding slightly to 37.5 million barrels per day thereafter.
Demand destruction stronger than expected
The rate of adjustment on the demand side has also surpassed expectations, and this is one of the main reasons oil prices haven’t surged further.
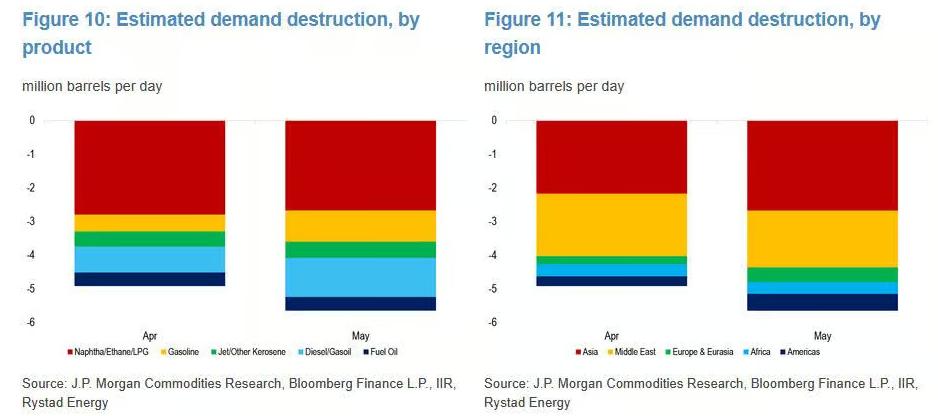
In March, global oil demand dropped by 1.9 million barrels per day year-on-year, far beyond the 600,000 barrels per day analysts had previously forecasted.
Regionally, the Middle East took the brunt: flight cancellations, stay-at-home orders, and petrochemical plant shutdowns led to a year-on-year demand drop of 1.4 million barrels per day there; gasoline demand hit its lowest since early 2021, while naphtha demand approached a decade low. Asia followed, with soaring petrochemical feedstock costs causing widespread shutdowns. Africa’s adjustment was unexpectedly swift — the last tanker from Hormuz only arrived in East Africa on March 28, and in North Africa even later on April 14, yet demand had already fallen by 200,000 barrels per day year-on-year, a stark contrast to analysts’ prior forecasts of a 300,000 barrels per day increase. Soft naphtha and diesel demand in Europe further contributed to a 200,000 barrels per day year-on-year drop.
Based on March data, JPMorgan revised down its demand forecasts for subsequent months: the April year-on-year demand drop was adjusted to 3 million barrels per day, and May to 4.2 million barrels per day, corresponding to “demand destruction” of 4.9 million and 5.6 million barrels per day, respectively.
However, not all segments are weakening. Ethylene capacity at Middle Eastern petrochemical plants has recovered about 50% from April’s lows; jet fuel has shown relative resilience — since late April, global flight numbers are down only about 1.5% year-on-year, with no large-scale cancellation wave as previously feared, and US and European air travel is providing support.
Inventory depletion: entering the pressure zone in late June, reaching bottom in September
Strategic reserves are the most important “buffer” in this crisis.
Since early March, global visible inventories (including crude and refined oil) have dropped by about 460 million barrels in total, equal to a daily depletion of approximately 4.6 million barrels. OECD countries have released around 400 million barrels from their strategic reserves into the market, with about half yet to be delivered.
Even if the US and Iran reach an agreement, it will take time for Hormuz to reopen, and inventory drawdowns will continue in the meantime.
Analyst calculations show: global inventories will enter a pressure zone in late June and approach operational bottoms in September — consistent with prior forecasts.
This represents the report's most critical timing: once inventories hit operational bottoms, the market will have no buffer, and any new supply shock could pass directly into prices.
What if the strait does not reopen in June?
JPMorgan’s base case: Hormuz reopens in June, Brent crude’s average annual price stays near $100/barrel, with the average only dipping below triple digits in December.
But if the blockade persists, the model projects: for every additional month of closure in Q3, the average price rises by about $5; for every additional month of closure in Q4, the average jumps by about $15. The larger Q4 increase is driven by accelerated inventory depletion — once the buffer is gone, price sensitivity to supply shortfall will skyrocket.
Kaneva raised a question in the report that deserves the market’s attention: When will market sentiment shift from “Is this it?” to “What if this isn’t over?”
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Micron executive: Storage determines AI limits, substantial new capacity will come after 2028
Micron executive Sumit Sadana stated that memory bandwidth and capacity have become the core factors determining the performance ceiling of AI systems. In the face of structural imbalances between supply and demand, Micron expects to increase capital expenditure to over $45 billion in fiscal year 2027, but due to process complexity, substantive new capacity will not be released until 2028. Additionally, long-term supply agreements are reshaping the industry's business model, and humanoid robots will trigger the next wave of massive demand.
Goldman Sachs warns top clients: AI momentum trading shows unprecedented cracks, recommends hedging
Goldman Sachs has issued a rare warning to top clients: deep structural cracks are emerging in AI momentum. The AI-themed basket has dropped nearly 45% from its peak, with the one-day performance gap between short-term and long-term momentum reaching a five-year high. Capital is accelerating its shift from semiconductors to software. Goldman Sachs explicitly recommends that investors with AI exposure start hedging.
Crypto prices
More


