
Oil prices fall back to "pre-Iraq war levels" — Is the market overreacting?

Brent crude oil fell below $77 per barrel this week, nearly wiping out all the geopolitical premium since the outbreak of the Iran war, marking the lowest level since the start of the conflict. However, several analysts warn that the futures market is currently pricing in a supply recovery that has not truly materialized, with a significant divergence emerging between the optimism in financial markets and the reality in the physical crude oil market.
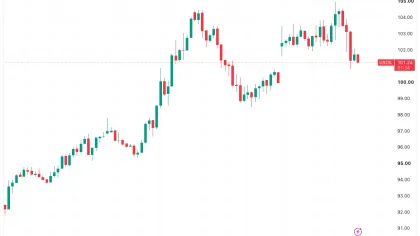
On Wednesday night, the US and Iran signed a 14-point framework memorandum of understanding. The US Central Command subsequently confirmed that the blockade on the Strait of Hormuz had been lifted, with reports of oil tankers passing through the waterway. Brent crude dropped intraday to $76.54 per barrel before clawing back to close at $79.85; WTI closed down 0.2% at $75.85, hitting its lowest level since the outbreak of the conflict. The US national average retail gasoline price fell below $4 per gallon, coming in at $3.999, though this is still about $1 higher than before the war.
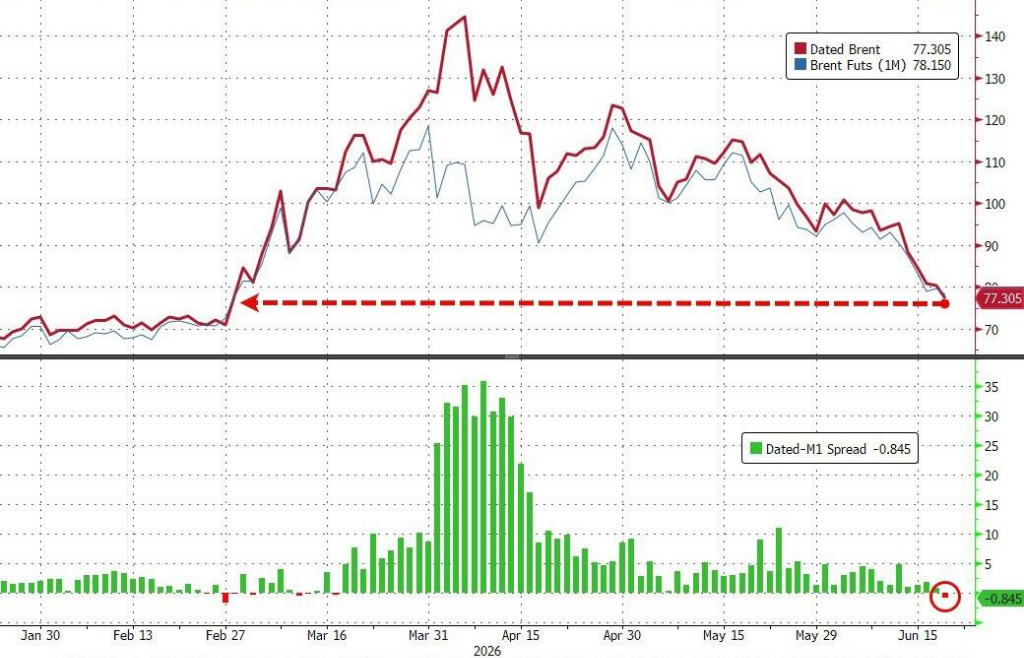
Since its May peak of over $100 per barrel, Brent has registered a cumulative drop of more than 25%, as markets quickly bet that a large volume of Middle Eastern crude is about to flood back into the global market.However, from the lack of shipping insurance and the fact that tanker freight is still three times pre-war levels, to the International Energy Agency (IEA) estimating that global inventories continue to deplete at a pace of nearly 4 million barrels per day, the fundamental reality is far more complex than what is being priced in by the markets.
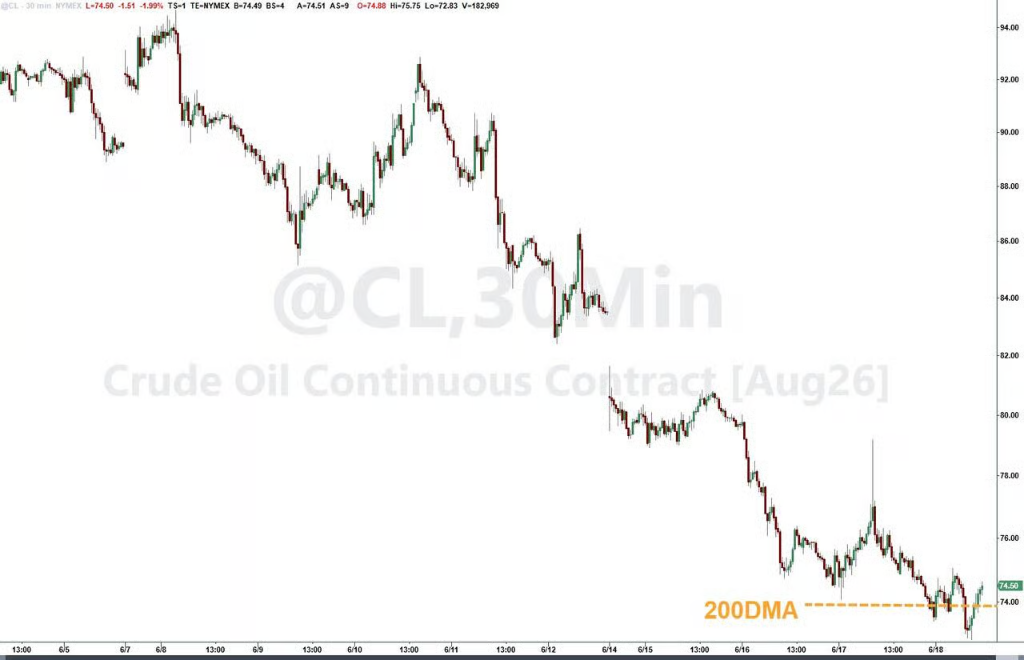
This race between the financial and physical markets is currently the main source of disagreement over oil price trends. Multiple institutional analysts believe the recent decline carries risks of overshooting, but some argue that expectations of Iran sanction relief are not yet fully priced in, and if confirmed, oil prices could face further downside pressure.
Hormuz Unblocked, Sentiment Drives Sell-off
The immediate trigger for the sharp drop in oil prices was the signing of the US-Iran memorandum of understanding. Under the framework agreement, Tehran will reopen the Strait of Hormuz—a passageway that, under normal circumstances, handles about a fifth of global daily oil trade—in exchange for Washington lifting the blockade on Iranian ports, removing oil sales sanctions, and opening a 60-day window for nuclear deal negotiations. Iran also pledged never to develop or acquire nuclear weapons.
The market’s reaction was immediate: sell first, ask questions later. Trump declared loudly on TruthSocial: "The oil is flowing... the stock market is roaring... you're welcome!"
Goldman Sachs analyst Yulia Zhestkova Grigsby estimated in a research report that Persian Gulf oil exports could recover to pre-war levels by the end of July, but also highlighted several obstacles to a full recovery. Kpler senior crude analyst Navin Das also stated that the price drop after the agreement reflected only a limited retracement of the geopolitical risk premium in the price curve, compounded by expectations for resumption of Hormuz flows, together putting pressure on spot prices.
The Shipping Market Isn’t Buying It: Freight Rates Triple Pre-war Levels
However, in stark contrast to the optimism in the futures market, the shipping market has yet to reflect this peace expectation.
According to reports, Sinopec attempted to charter a Very Large Crude Carrier (VLCC) to load Iraqi crude between June 25 and 30 this week, receiving six offers, all at rates nearly triple the pre-war levels, with no deal ultimately struck. PetroChina's reasoning was direct: "There are tankers, but they're too expensive, and there's no guarantee you can get through the strait." Meanwhile, Indian Oil received zero bids on its concurrent charter tender; Sinochem is still seeking a vessel.
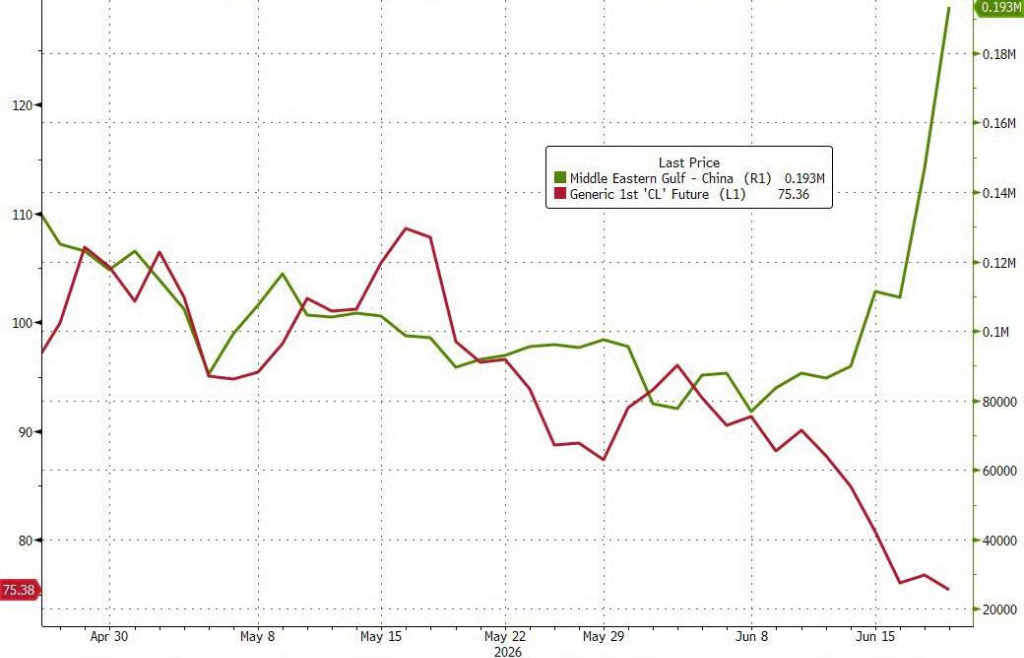
Argus Media’s Gulf and Middle East market editor, Nader Itayim, pointed out that the market is overly optimistic about the impact of the agreement, likely overestimating the scale and speed of supply normalization. "Although there is oil available for export in the GCC region, the additional supply may not arrive immediately," he said, "and before flows return to normal, logistical bottlenecks remain to be overcome."
Goldman analyst Yulia Zhestkova Grigsby also wrote that many shipowners remain cautious about transiting the strait, shippers’ risk aversion is a constraint, and Iran’s geopolitical goals during the 60-day nuclear talks add uncertainty.
Inventory Data Warns: Fundamentals Do Not Support Optimism
The fundamentals in the physical crude oil market have drawn a clear warning line for this sharp decline.
The IEA estimates that since the end of February, when the conflict broke out, global inventories have been depleting at nearly 4 million barrels per day. US crude inventories have dropped by more than 50 million barrels in the past nine weeks, with Cushing tank levels hovering close to what most analysts consider the operational minimum. For countries that have been drawing on strategic and commercial reserves for months, replenishment will eventually be necessary.
Looking at the Brent futures curve, for oil prices to return to pre-war lows ($70 per barrel), that is not expected until March 2031—highlighting a major gap with the aggressive pricing seen in today’s futures markets.
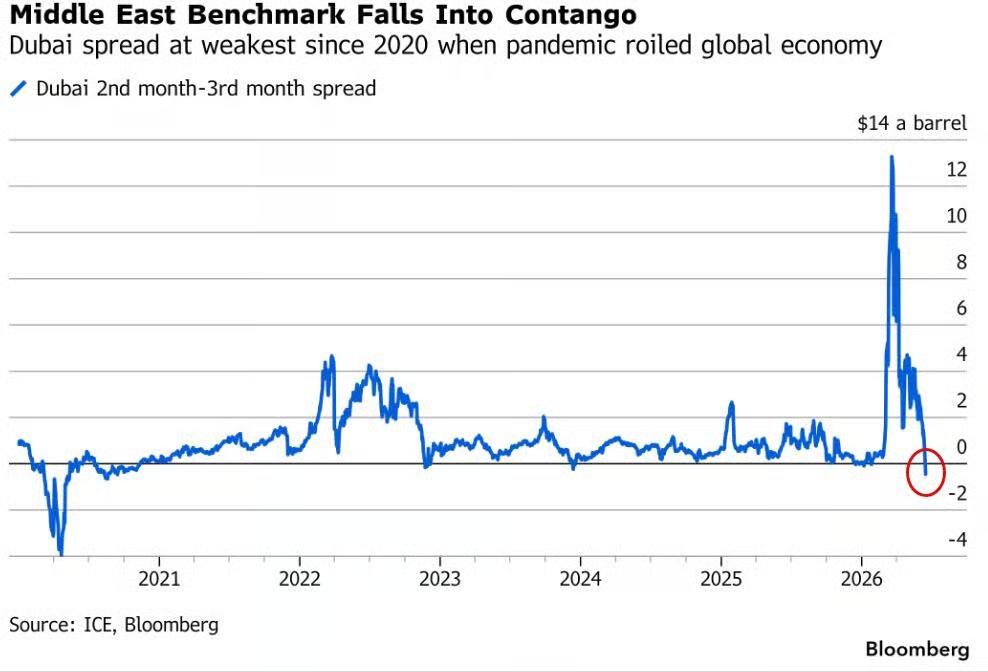
Bloomberg also notes that should Hormuz flows truly resume, the Asian market faces another challenge: Asian refiners have previously replaced disrupted Middle Eastern crude with US and other alternatives, leading to some reduction in throughput, and now must contend with a sudden influx of Persian Gulf oil. This has already pushed the Middle East crude futures curve into a bearish contango structure, with the market now pricing for near-term oversupply rather than shortage.
The Agreement Framework Still Has Uncertainties
Beyond the pace of supply recovery, the agreement itself contains several ambiguities, adding extra uncertainty to the market.
The memorandum states that commercial vessels will be "exempt from passage fees for only 60 days," but Trump told the media that the strait would remain "free to transit" even after 60 days. This was not written explicitly in the agreement. Itayim also emphasized that this is not a comprehensive peace deal the market can fully rely on, but rather a temporary framework aimed at de-escalation and opening a window for further talks. As such, markets will continue to price in a certain amount of risk premium.
Kpler analyst Navin Das highlighted another aspect: the far end of the price curve has begun to partially reflect the possibility of Iran sanctions relief, but this factor is not fully priced in—should official confirmation come after the 60-day negotiation window, oil prices could still face additional downside pressure.
Consensus across multiple analyses points to the same core contradiction: the financial markets have taken the agreement’s signing as a signal and quickly priced in supply recovery in one swift move; the physical market—including shipping insurance, tanker scheduling, mine clearance at oil fields, and production restart—operates on a totally different timeline. Currently, the market is trading a preliminary framework deal as if it were a fully completed production restart plan, while the physical market is still waiting for it to actually materialize.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Gold gets squeezed by 5% Treasury yields as FOMC week begins
Addus Advances M&A Strategy With Deal for AccentCare Personal Care Business
Bitcoin tops $79K, oil falls as Trump says Iran war could end
Stellar Advances Institutional Stablecoin Transfers
Crypto prices
More


