
Want a rate cut? The Missing 20 Basis Points: How Statistical Revisions Created a Cooling PCE

On June 26, the U.S. Bureau of Economic Analysis (BEA) announced that it would implement systematic adjustments to the price calculation methods for the three core components of PCE in the annual GDP revision on September 30. These adjustments will cover computer software and accessories, portfolio management and investment advisory services, and legal services, with historical data revisions tracing back to 2021.
As the inflation gauge most closely watched by the Federal Reserve, with the current year-over-year core PCE as high as 3.4%, this adjustment to the PCE’s statistical algorithm by BEA is not neutral but carries a clear downward bias. This change is expected to reduce the year-over-year core PCE reading for May by around 20 basis points to 3.2%, making a surgical downward adjustment to inflation readings from the data source itself; the forecast for core PCE in Q4 2026 will also be revised from 3.1% down to nearly 2.8%. This is significantly below the Fed’s median forecast of 3.3%.
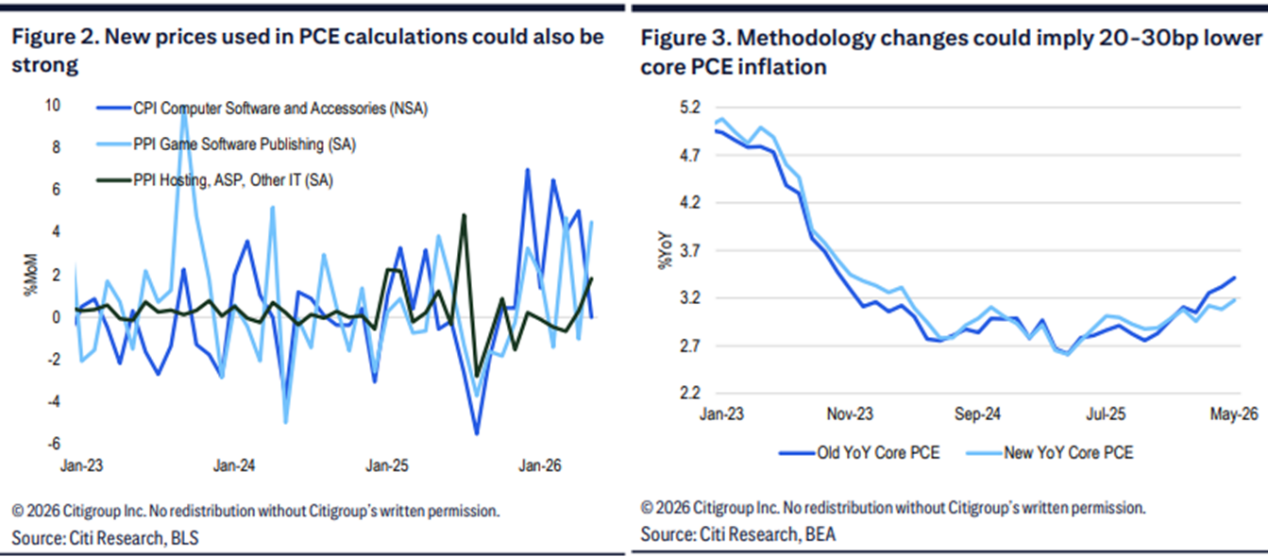
Such a “paper-based” cooling of inflation data will bring two profound macro consequences: First, the divergence between inflation indicators will intensify further. Since core CPI is unaffected by this adjustment, in the coming months, core CPI may show more resilience compared to core PCE, highlighting the discrepancy between different fundamental inflation measurement methods. Second, the revised components are all major positive contributors to core PCE inflation, with a clear bias in the choice of items, revealing an intention to suppress inflation readings.
More critically, the new method will no longer be directly linked to publicly available price indexes, with significantly reduced transparency, making it difficult for external organizations to independently verify the official data. This not only undermines the credibility of statistical indicators, but also makes inflation data more susceptible to influence from political cycles, posing the risk of concealing genuine inflationary pressures.
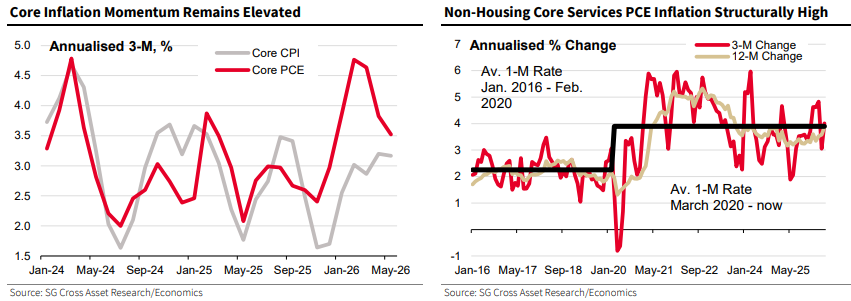
Paper-Based Cooling: How Do 20 Basis Points Disappear Out of Thin Air?
This PCE algorithm revision is essentially a statistical technique adjustment that filters out short-term economic volatility by altering the “price proxy variables.”
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
High interest rates are not the "end" of US stocks? Is profitability the real key?
JPMorgan believes that profit growth is the key factor determining the resilience of U.S. stock valuations. Data since 1950 shows an "inverted U-shaped" relationship between the 10-year U.S. Treasury yield and S&P 500 valuations. Based on current profit levels, yields would need to reach about 5%-6% to significantly compress valuations. As long as profit growth remains above 15%, there is still room for valuations to be re-rated. If the yield curve steepens in a bear market, cyclical sectors such as energy and financials will benefit more; if it flattens, technology stocks will have a relative advantage.
The "Outlier" Investment Art in the New Era of Berky

Chevron (CVX.US) explores alternative hedging for Middle East supply disruptions: targets Argentina and the Mediterranean to drive global LNG growth, seeks deal with India
Chevron is focusing on Argentina and the Mediterranean region, seeking global growth in liquefied natural gas, and plans to reach an agreement with India.

Expert Drops a Bullish Yet Scary Prediction for ETH Price in 2027, $10,000 ATH to $800 Black Swan Event?
Crypto prices
More


