
How will the market perform during the remainder of 2026?

Huitong Net, October 14 – What factors could trigger a major gold correction? Which core driving forces will dominate the market for the remainder of 2026? This article will outline these variables and analyze potential market performances under different scenarios.
Last weekend, I discussed the outlook for gold and the logic of currency devaluation trades. I am optimistic about gold and other precious metals because the fiscal policies of most developed economies have taken an unsustainable trajectory. Readers are more concerned about what factors could cause gold to undergo a significant pullback and which core drivers will lead the market for the rest of 2026. This article will lay out these variables and analyze likely market outcomes across various scenarios.
In my view, two main risk factors will dominate the market for the remainder of 2026. The first is oil prices—are we about to witness another surge in oil prices? The second is the situation in France, which appears to be evolving independently and could become a distinct specific risk. Of course, there are other market risks. The Federal Reserve under Waller is one example, as its policy stance could unpredictably shift from dovish to hawkish. There's also the midterm elections and the artificial intelligence bubble, which, if it bursts, could shock the market. However, for the period under discussion—the final three months of the year—I subjectively judge that oil prices and the situation in France are the core variables that warrant the most attention.
The scenario matrix above shows my assessment of the likely trends for the US dollar, the euro, the 10-year US Treasury yield, gold, and the S&P 500 Index (SPX) under different scenarios. The matrix's vertical axis distinguishes between two situations: oil prices continuing to rise (upper row) and oil prices declining (lower row). The horizontal axis has two cases: the left denotes a full-blown crisis in France, while the right indicates France barely maintaining the status quo (which is the best the market can hope for). The blue percentages represent my subjective probabilities for each of these four scenarios.
In my opinion, current oil prices are relatively high: the supply side is much better than in March or April, yet prices have returned to those springtime levels. Thus, I estimate there is a 70% chance that oil prices will fall from here and only a 30% chance that they will continue to rise. I see a 30% probability of a full-fledged crisis in France, and a 70% chance they just about hold things together.
The two scenarios with the greatest market volatility are in the upper left and lower right quadrants of the matrix.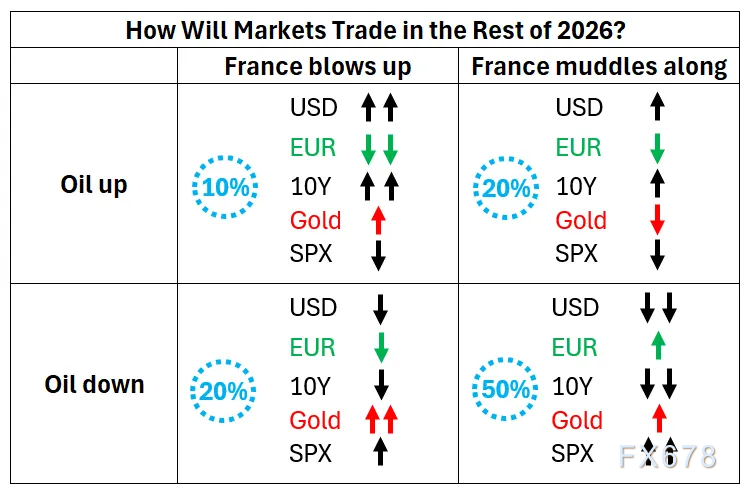
Upper left quadrant: Oil prices surge while France erupts in crisis. The dollar will strengthen sharply, and European funds will flock into safe-haven assets, driving gold higher.
The exact opposite scenario is oil prices falling while France manages to keep things stable (lower right quadrant). The market will adjust for the likelihood that the Federal Reserve will not hike rates, the dollar will weaken significantly, and the S&P 500 will become the biggest beneficiary.
For gold, the lower left quadrant is the most noteworthy: oil prices drop, but France still faces a crisis. On one hand, declining oil prices support gold; on the other, turmoil in the eurozone fuels safe-haven demand, creating a dual boost for the gold price.
In the most probable scenario (lower right quadrant), the S&P 500 has significant upside, while both the US dollar and the 10-year US Treasury yield are likely to decline.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Storage stocks suffer growing pains from a narrative shift! Roundhill suggests a "barbell strategy": large-cap growth plus "halo stocks"
Drew Pettit, Chief Investment Strategist at Roundhill Investments, stated that the market does not favor stocks with a transitional narrative, and currently, storage stocks are in such an awkward position.
The largest single-week net purchase in fifteen years! Citadel analyst: Retail investors are buying AI stocks again
Retail investors are bottom-fishing AI stocks, with a net purchase of $9.1 billion in one week, marking a 15-year record! According to Citadel Securities data, funds are highly concentrated in semiconductors and AI infrastructure. However, this is not a broad-based buying frenzy, but rather a directional overweight, with buying skewed to the 90th percentile of the past year.
Australian Dollar climbs as Fed’s Williams push the brakes on rates
Microsoft adds over $130 billions in new data center leases, plans to more than double computing power
Microsoft plans to increase its global data center capacity from approximately 12 GW to over 38 GW. In a single quarter, it added over $130 billions in new lease agreements, bringing its total uncommitted lease commitments to $329.1 billions—a more than 67% increase over the previous quarter and the largest quarterly jump in leasing on record. This move is aimed at alleviating the long-term computing power bottleneck, as capacity shortages have already caused some customers to turn to competitors.
Crypto prices
More


