
Morgan Stanley research report interpretation: The HDD cycle has not ended, but the market is pricing it as if it has peaked

Written by: Rita
The market values hard disk drives (HDDs) at an 8x price-to-earnings ratio, implying a cycle peak in FY28. Morgan Stanley offered a contrary view in its report on October 20, 2026: the cycle is not over, and this valuation is overly punitive.
Demand is accelerating. Nearline HDD spot prices are between 4 and 7 cents per GB, and hybrid nearline contract prices are about 1.5 cents per GB. Industry supply is expected to be short around 400 exabytes (EB) in CY27/CY28, and 300EB in CY26. Customers are expanding from core cloud service providers (CSPs) to AI laboratories, with the latter aiming to purchase 100% of the available EB.
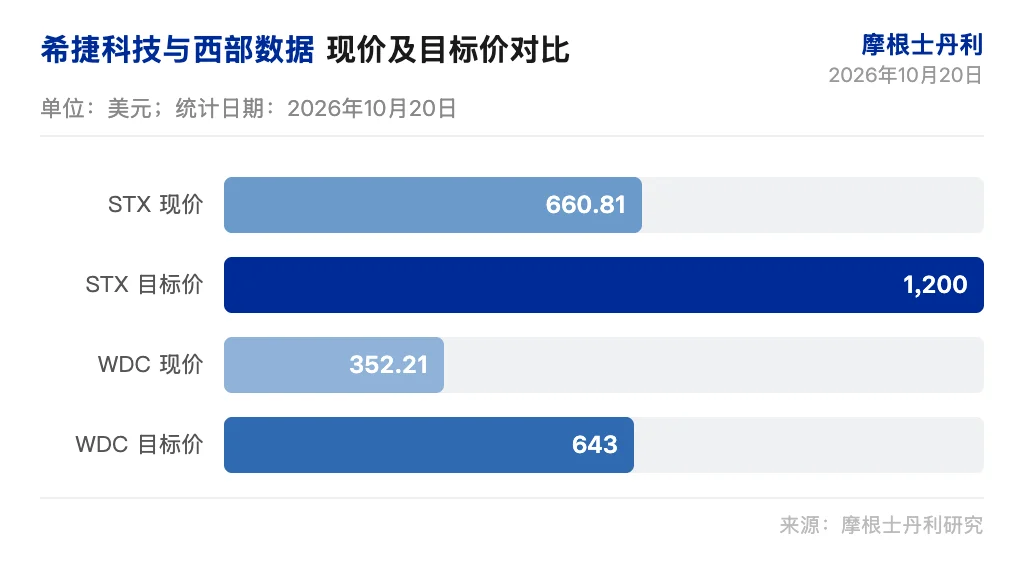
Morgan Stanley reiterates its Overweight rating on Seagate Technology (STX) and Western Digital (WDC), with STX regaining status as the top pick in IT hardware. Target price for STX is $1,200 and for WDC is $643. WDC has lower buy-side expectations and better tactical setup in its financial reports.
8x P/E Ratio Implies Cycle Peak
Morgan Stanley uses FY28 earnings and assumes an 80% drop in solid-state drive (SSD) prices to reverse engineer current valuations. An 8x P/E implies that HDD earnings peak in FY28, with SSD prices dropping 80% from C2Q26 levels. Morgan Stanley believes this assumption is overly punitive.
HDD demand is accelerating, supply shortages are expanding, and spot prices remain far above contract prices. Non-nearline HDD prices have increased 15% to 30% quarter-on-quarter. There is positive asymmetric valuation.
Morgan Stanley lowers its target multiple from 20x to 15x (STX) and 14x (WDC), reflecting industry structure and uncertainty in AI financing. Target prices are $1,200 for STX (15x FY28 EPS of $80.10) and $643 for WDC (14x FY28 EPS of $45.95). Current price for STX is $660.81, for WDC is $352.21.
Spot Prices Much Higher Than Contract Prices
Nearline HDD spot prices are between 4 and 7 cents per GB, and hybrid nearline contract prices are about 1.5 cents per GB. Customers want to purchase 100% of the EB, but supply shortages limit procurement scale. Shortages in storage capacity are pushing up spot prices.
Non-nearline HDD prices have increased 15% to 30% quarter-on-quarter. Seagate has been more aggressive than Western Digital in capturing spot pricing. Demand has expanded from core CSPs to AI laboratories. Toshiba is constrained by media and equipment, and its CY27 capacity has already sold out, resulting in more aggressive pricing. Morgan Stanley feels comfortable with risks related to Toshiba.
December Quarter EPS Above Consensus
Seagate Technology's EPS for the September quarter is expected to be $7.50 versus market consensus of $7.41; Western Digital's September quarter EPS is $4.13 versus consensus of $4.09. Seagate's December quarter EPS is expected to reach $9.54, 12% above consensus. If spot pricing assumptions are more aggressive, December EPS could be another 5% higher.
Western Digital's December quarter EPS is expected to be $5.25, 10% above consensus. If spot pricing assumptions are more aggressive, December EPS could reach $5.67. WDC buy-side expects revenue of $4.75 to $4.95 billion, gross margin of 59.5% to 61.0%, and EPS of $5.20 to $5.60. WDC guidance is typically conservative.
Morgan Stanley believes WDC's financial report tactics are better due to lower buy-side thresholds. STX is still 10% above the "close-your-eyes-and-buy" valuation level ($595 at 10x CY27 EPS), while WDC is only 3% above ($343).
Cycle Not Over, but the Path Is Murkier
Morgan Stanley admits that the HDD catalyst path is murkier than a month ago. The market has uncertainties about supplier rationality and AI funding sources, which financial reports cannot resolve. The target multiple is cut by 5 to 6 basis points.
Demand checks support outperformance and upward revisions to guidance. Morgan Stanley focuses on four questions: whether STX/WDC will adjust capacity plans in response to Toshiba's targets; whether they prioritize profits over market share; whether the supply/demand gap is widening; and whether more aggressive pricing is seen. The answers to these questions may not return the stocks to their narratives from four months ago but can help investors recognize that some risks have been priced in.
Morgan Stanley reiterates Overweight for STX and WDC, with STX returning to Top Pick. The market is pricing the end of the cycle, while Morgan Stanley prices in its continuation.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Piper Sandler lowers Netflix target price to $78
Citi raises SpaceX target price from $200 to $240
Crypto prices
More


