
Microsoft Q3 Earnings Preview: Azure Capacity Release and AI Monetization Validation
 2026/10/27 04:47
🔥 US Stock Hotspot Radar is Live! Content: 3 major themes + 6 selected stocks + 7 key events. Where are this week’s opportunities? Click the link to see all 22 trading directions in one chart →
1. Investment Highlights
Microsoft (MSFT.US) will report its fiscal 2027 Q1 results (calendar 2026 Q3) after the U.S. market close on October 28, 2026. Wall Street consensus expects revenue of approximately $89.9–91.2 billion (+16%–17% YoY), net income of $35.2–35.8 billion (+27.5% YoY), Azure growth of 45%–46%, and capital expenditure of $50.0–51.5 billion. The stock has recently hit all-time highs, supported by improved guidance and capital inflows. The market is closely watching whether Azure can reaccelerate on capacity release, the progress of AI monetization, and the resilience of free cash flow and forward guidance amid elevated spending.
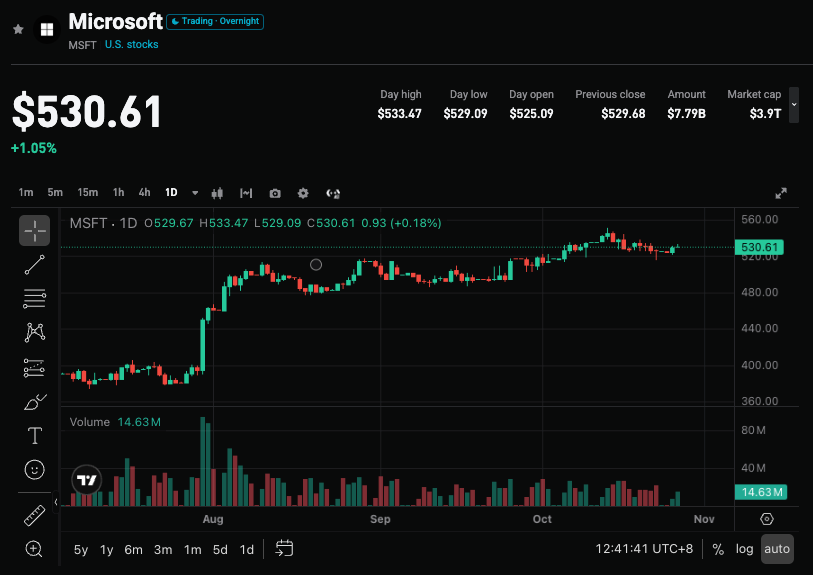
Focus 1: Can Azure Growth Reaccelerate on Capacity Release?
Azure remains the core growth engine of Intelligent Cloud. Growth had previously been constrained in the 38%–40% range as a portion of newly arrived GPUs was prioritized for Copilot and internal R&D. Supply constraints are easing this quarter: roughly 31 new data centers were added in the period (about 88 for the full year), approximately 1 GW of new capacity came online, and GPU deployment lead times in the largest regions shortened by nearly 50%. Higher utilization is allowing capacity to convert into revenue within the same quarter. Wall Street hopes growth accelerates to 47% or approaches 50%; some estimates point to 46%–47%. Achieving this would validate demand resilience and the easing of supply bottlenecks; a result at or below 45% could reinforce concerns about slower growth.
Focus 2: AI Monetization Progress and Contribution from Productivity Business
Productivity tools remain the largest contributor to both revenue and profit, with operating margins around 60%. M365 Copilot paid seats have surpassed 30 million (up from roughly 20 million last quarter, more than doubling sequentially), and the number of large customers has increased more than 7x year-over-year. GitHub has reached 50 million total users, with paid subscribers exceeding 4.7 million (+75% YoY). After the full shift to usage-based pricing, Copilot revenue grew more than 60% sequentially, and ARR has exceeded $1 billion. Faster-than-expected monetization helps ease concerns about over-reliance on Azure, though investors will watch whether higher penetration continues to translate into high-quality revenue and profit.
Focus 3: Capex, Free Cash Flow, and Depreciation Pressure
Wall Street expects capital expenditure of $50.0–51.5 billion this quarter and approximately $240 billion for fiscal 2027. Microsoft has modestly lowered its spending outlook and committed to positive free cash flow, but elevated outlays combined with longer depreciation lives (data center buildings extended from 15 to 25 years) may flatter near-term results. Impairment risk and off-balance-sheet lease commitments (uncommenced leases of roughly $329.1 billion) also warrant attention. Free cash flow could fall below $10 billion or even lower. The shift from aggressive expansion to more precise investment is underway, but the return cycle and cash-flow health remain key tests.
Focus 4: Next-Quarter Guidance and Full-Year Outlook
The market expects next-quarter (calendar 2026 Q4 / fiscal 2027 Q2) revenue of $95.5–96.0 billion, with Azure growth guidance of 44%–47%. Some estimates are broadly in line on revenue but slightly more cautious on Azure. Backlog is consensus around $720 billion; a meaningful increase would improve visibility. Full-year capex and Azure guidance that deviate meaningfully from expectations (particularly if Azure falls short of the ~50% growth some investors hope for) will likely drive sentiment and the pace of valuation recovery.
3. Risks and Opportunities
Upside Catalysts:
- Azure growth reaches or exceeds 47%, confirming reacceleration after capacity release.
- Total revenue and net income beat consensus, Copilot/GitHub monetization metrics are strong, and next-quarter or full-year guidance is raised.
- Backlog grows significantly, capex is precise, and free cash flow exceeds the most pessimistic expectations.
Downside Risks:
- Azure growth is merely in line with or below 45%, or next-quarter guidance is conservative, reinforcing supply/demand concerns.
- Capex comes in above expectations while free cash flow is under heavy pressure or approaches zero, raising questions about the return cycle.
- AI monetization progress slows, or depreciation/lease-related risks are emphasized, pressuring valuation.
4. Trading Strategy Suggestions
Bull Case: If Azure reaccelerates meaningfully, overall results beat expectations, and management comments positively on capacity monetization and AI uptake, the stock could extend its strength and reinforce Microsoft’s position as a leading AI cloud and productivity platform.
Bear Case: If key metrics are merely in line, Azure guidance falls short of higher market hopes, or free cash flow/spending concerns emerge, profit-taking could occur against a backdrop of elevated valuation.
Key Metrics to Watch:
- Total revenue, net income, and year-over-year growth rates
- Azure growth rate and next-quarter guidance
- Capital expenditure level and free cash flow
- Copilot seats/ARR progress and backlog
Actionable Ideas: On a beat-and-raise outcome, consider looking for pullback entry opportunities. If results are muted or guidance is soft, watch for near-term volatility and avoid chasing strength. Position sizing and stop-losses should be adjusted according to individual risk tolerance.
Disclaimer: The above content is for reference only and does not constitute investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Why Is Bitcoin Stuck Near $80K as Strategy Diverts $205M to Preferred-Share Buybacks?
The rebound in the UK stock market faces the "budget test"! Tax increases, government bond yields, and consumer pressure affect market sentiment
As global investors regain confidence in the UK market, the Autumn Budget to be announced this Wednesday will serve as a major test for the country's stock market.

XRP TD Sequential Buy Signal — Last Three Led to 18%–31% Rebounds
Crypto prices
More


